 By
Published: 11/12/2026, Updated 11/12/2026
You've checked your credit on Credit Karma’s free app for a couple of years, mostly when a notification reminded you to. Now you're thinking about refinancing your mortgage, and the loan officer says they'll pull your credit before quoting a rate. When you see their report, it includes information from all three bureaus, but up until then you’ve only been reviewing two in the free app. That's an uneasy thing to realize right before a big decision, but comparing what each kind of product covers comes down to a few clear differences.
Credit Karma is a free product that shows credit reports and VantageScore 3.0 scores from two bureaus, Equifax and TransUnion, and is supported by third-party advertisers. ScoreSense is a paid subscription that gives you credit reports and scores from all three bureaus, including Experian, plus daily monitoring of your Experian credit report and access to live credit specialists by phone and chat.
How Credit Karma and ScoreSense Compare at a Glance
Here's the side-by-side, limited to what each company says about its own product.
|
FEATURE |
CREDIT KARMA |
SCORESENSE |
|---|---|---|
|
Cost |
Free to use; supported by compensation from third-party advertisers |
Paid subscription with a 7-day free trial; full terms shown at signup |
|
Credit bureaus |
Equifax and TransUnion |
Equifax, Experian, and TransUnion |
|
Score model |
VantageScore 3.0 |
VantageScore 3.0 |
|
Report and score updates |
Checks Equifax and TransUnion reports daily |
Updated reports and scores from all three bureaus once a month |
|
Monitoring and alerts |
Alerts for important changes on Equifax or TransUnion reports |
Daily monitoring of your Experian credit report, with alerts |
|
Support |
Online Help Center |
Live credit specialists by phone and chat |
Both products show VantageScore 3.0 scores, so the scores are calculated with the same model. The differences are how many of your credit reports you see, how each product is paid for, and what kind of help comes with it.
Bureau Coverage: Two Reports or Three
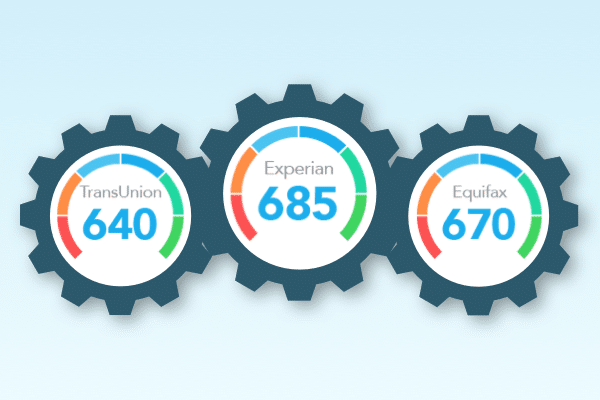
This is usually the question that starts the search: does it matter whether you see two credit reports or three? Equifax, Experian, and TransUnion each keep their own report on you, and lenders aren't required to report to all three, according to Experian. So an account can appear on one report and be missing from another.
Credit Karma gives a simple example on its own site: if a lender reports your car loan to Experian and TransUnion but not to Equifax, your Equifax report won't include that loan. The reverse can happen too. A credit union auto loan reported only to Experian could show up on your Experian report and nowhere else.
That doesn't make two-bureau scores wrong. They reflect the two reports they're built from. What a two-bureau view can't show is information that appears only on your Experian report. ScoreSense delivers updated reports and scores from all three bureaus once a month, so your Experian report sits alongside the other two.
Bureau coverage is one difference. The other big one is how each product pays for itself.
How Each Product Is Paid For
Credit Karma is free to use. It's supported by compensation from third-party advertisers, which is why you may see offers for financial products, such as credit cards or loans, alongside your scores.
ScoreSense is a paid subscription with a 7-day free trial; full terms are shown at signup. You can cancel by chat in your account or by calling 1-800-972-7204 during Customer Care hours, which run Monday through Friday 8 AM to 8 PM, Saturday 8 AM to 5 PM, and Sunday noon to 6 PM Central Time. Online cancellation may also be available, depending on your state.
The terms shown at signup spell out the trial’s length, what happens when it ends, and the cancellation options available to you.
Once you know what each one costs, the next question is what you get day to day.
Support and Monitoring Features
Both products watch for reported changes. Credit Karma alerts members to important changes on their Equifax or TransUnion reports, and it offers free identity monitoring that alerts you if your personal information is exposed in a data breach. ScoreSense includes daily monitoring of your Experian credit report with alerts, along with credit insights and educational tools.
So what happens when an alert shows up and you're not sure what it means? Credit Karma points members to its online Help Center to reach its support team. ScoreSense members have access to live credit specialists by phone and chat, who can answer general credit questions, such as what a hard inquiry is or what different sections of a credit report mean.
During a refinance, that might look like an alert about a new inquiry a few weeks before closing. A specialist can explain how a hard inquiry generally differs from a soft one and answer general questions about credit inquiries.
Brian Sullivan, Vice President of Marketing at ScoreSense, explains why the company built its product around people:
"Credit affects many of life's biggest financial decisions, yet most people are never formally taught how it works. When we spoke with customers, one message came through clearly: they wanted someone they could talk to about credit questions. That's why ScoreSense invested in real people who can provide live support. Our focus is helping consumers better understand their credit and make informed decisions with confidence."
Brian Sullivan, Vice President Of Marketing, ScoreSense
With the features side by side, the choice comes down to your situation.
Which One Fits Your Situation
Each product offers something different. The better fit depends on what you want to see and how much help you want while you look.
- A free, two-bureau product may fit if your primary goal is to have a regular look at your Equifax and TransUnion reports and scores for free, and you're comfortable with a product supported by advertisers.
- A three-bureau subscription may fit if you want your Experian report and score alongside the other two each month, daily monitoring of your Experian report, and a person to call or chat with about general credit questions.
If you're preparing to refinance, reviewing all three reports before you apply can help you identify unfamiliar information, such as an account that appears on only one report. Checking your own reports and scores is a soft inquiry, so it doesn't affect your credit scores.
When you do look, go report by report and compare the basics: the accounts listed, their balances, and their payment history. A card you paid on time every month but that shows a 30-day late payment on one report, or a loan you don't recognize, is the kind of difference worth following up on. Disputing mistakes on your credit report is free, and our guide to disputing credit report errors walks through each bureau's process.
Frequently Asked Questions
Is Credit Karma free?
Yes. Credit Karma is free to use and is supported by compensation from third-party advertisers.
Which credit bureaus does Credit Karma use?
Credit Karma shows credit reports and VantageScore 3.0 scores from Equifax and TransUnion. ScoreSense also uses VantageScore 3.0, with scores from all three bureaus.
Does ScoreSense include Experian?
Yes. ScoreSense provides credit reports and scores from all three major credit bureaus: Equifax, Experian, and TransUnion.
Can I talk to a person at ScoreSense?
Yes. ScoreSense members can reach live credit specialists for general credit questions by phone at 1-800-972-7204 or by chat in their account dashboard.
Is there a ScoreSense free trial, and how do I cancel?
ScoreSense offers a 7-day free trial, with full terms shown at signup. Members can cancel by chat or by calling 1-800-972-7204 during Customer Care hours: Monday through Friday 8 AM to 8 PM, Saturday 8 AM to 5 PM, and Sunday noon to 6 PM Central Time.
The Bottom Line
Credit Karma and ScoreSense both show VantageScore 3.0 scores. They differ on coverage, cost, and support. Credit Karma is free and covers Equifax and TransUnion. ScoreSense is a paid subscription that adds your Experian report and score, daily monitoring of your Experian report, and live credit specialists by phone and chat. If you're heading into a refinance and want all three reports in front of you first, here's where ScoreSense comes in.
ScoreSense provides credit reports and scores from all three major credit bureaus, with daily monitoring of your Experian credit report and alerts, credit insights and educational tools, and access to live credit specialists by phone and chat. It's a paid subscription with a 7-day free trial; full terms shown at signup.
About the Author
Brian Sullivan is Vice President of Marketing at One Technologies, the company behind ScoreSense, where he has worked since 2007.
Sources
Sources checked Oct 27, 2026.